
When investing in mutual funds, investors often have to choose between direct mutual fund plans and regular mutual fund plans from their demat accounts. Both invest in the same underlying mutual fund scheme, but the main difference is how the investment is made and whether a distributor or intermediary is involved.
This difference can affect the expense ratio, returns, services and the way an investor manages the investment.
A direct plan may be suitable for investors who can research and manage their mutual fund investments themselves. A regular plan may be more suitable for investors who want assistance from a mutual fund distributor or intermediary.
Understanding the difference can help you choose the option that fits your investment approach.
What Is a Direct Mutual Fund?
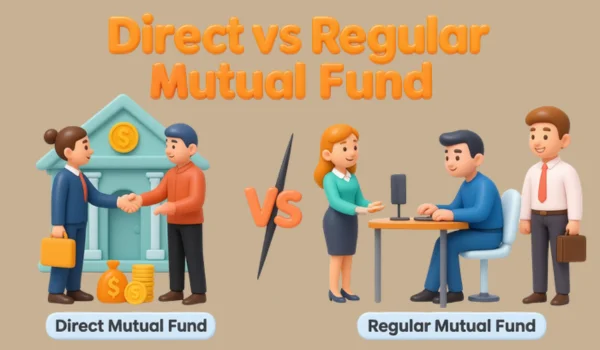
A direct mutual fund plan is purchased directly from the mutual fund company or through a platform that allows investors to invest without a distributor.
In a direct plan, there is no distributor commission built into the expense ratio.
For example, an investor can invest in a direct plan through the asset management company’s website or app, subject to the available investment options and process.
The investor is generally responsible for selecting schemes, deciding how much to invest and monitoring the portfolio.
What Is a Regular Mutual Fund?
A regular mutual fund plan is purchased through a mutual fund distributor or intermediary.
The distributor helps investors select and purchase mutual fund schemes and may provide ongoing assistance.
The mutual fund company pays distributor commissions according to the applicable distribution arrangement. These costs are reflected in the expense structure of regular plans.
As a result, the expense ratio of a regular plan is generally higher than the corresponding direct plan.
Direct vs Regular Mutual Fund: Key Differences
| Feature | Direct Mutual Fund | Regular Mutual Fund |
| Distributor involved | No | Yes |
| Expense ratio | Generally lower | Generally higher |
| Distributor commission | Not included | Included in the regular plan’s expenses |
| Investment decision | Investor manages it | Distributor may provide assistance |
| Returns | Potentially higher over long periods due to lower expenses | May be slightly lower because of higher expenses |
| Guidance | Limited unless obtained separately | Distributor support may be available |
| Suitable for | Self-directed investors | Investors seeking assistance |
| Portfolio management | Investor’s responsibility | Investor may receive distributor assistance |
What Is the Difference in Expense Ratio?
The expense ratio represents the expenses charged by a mutual fund scheme for managing and operating the fund.
Direct plans generally have a lower expense ratio because they do not include distributor commissions.
Regular plans have a higher expense ratio because the distribution arrangement involves compensation for the intermediary.
Even a small difference in annual expenses can affect long-term returns because the cost continues to apply while the investment remains in the fund.
Direct Mutual Fund vs Regular Mutual Fund: Return Difference
Both direct and regular plans of the same mutual fund scheme generally invest in the same underlying portfolio.
However, their net returns can differ because of differences in expenses.
For example, if a direct plan has a lower expense ratio than its regular counterpart, more of the fund’s investment return remains with the direct-plan investor after expenses.
The difference may appear small in a single year, but over many years, the impact can become more meaningful because of compounding.
However, investors should not assume that a direct plan will always produce a higher return before considering all relevant factors. Market performance depends on the underlying scheme and its investments.
Is Direct Mutual Fund Always Better?
Not necessarily.
A direct plan can be more cost-efficient, but it also requires the investor to take greater responsibility for investment decisions.
You may need to:
- Research mutual fund schemes
- Compare risk levels
- Understand investment objectives
- Select suitable funds
- Decide asset allocation
- Monitor your portfolio
- Review investments periodically
- Handle changes or redemptions yourself
If an investor lacks the knowledge or time to do these things, professional or distributor assistance may provide value.
Advantages of Direct Mutual Funds
- Lower Expense Ratio
The absence of distributor commissions generally results in a lower expense ratio compared with the corresponding regular plan.
- Potentially Better Long-Term Returns
Lower expenses can leave more of the investment return with the investor over the long term, assuming the underlying scheme is the same.
- No Distributor Dependency
Investors can select and manage their investments independently.
- Greater Cost Transparency
Investors who are comfortable researching funds can directly compare schemes and their costs.
Disadvantages of Direct Mutual Funds
- No Distributor Assistance
You generally do not receive the same distributor-led guidance that comes with a regular plan.
- More Responsibility
You must make your own investment decisions.
- Requires Financial Knowledge
Understanding mutual fund categories, risk, asset allocation and portfolio performance is important.
- Time Commitment
Investors need to spend time researching and reviewing their portfolio.
Advantages of Regular Mutual Funds
- Access to Guidance
A distributor can help investors understand different mutual fund options and select investments based on their needs.
- Convenient for Beginners
Investors who are unfamiliar with mutual funds may find the additional support useful.
- Ongoing Assistance
Depending on the distributor, investors may receive assistance with transactions, portfolio reviews and other investment-related matters.
- Useful for Investors Who Lack Time
People who do not want to independently research every investment decision may prefer the convenience of distributor support.
Disadvantages of Regular Mutual Funds
- Higher Expense Ratio
Regular plans generally have higher expenses than corresponding direct plans because of distribution costs.
- Lower Net Returns Compared With Direct Plans
If the underlying fund performs similarly, higher expenses can result in lower net returns over time.
- Dependence on Distributor
The quality of guidance depends on the distributor or intermediary you choose.
Direct vs Regular Mutual Fund: Which Is Better for Beginners?
For a beginner, the answer depends on their financial knowledge and willingness to learn.
A beginner who wants professional assistance and does not feel comfortable selecting mutual funds independently may prefer a regular plan.
However, a beginner who is willing to learn about mutual funds and manage investments independently may choose a direct plan to reduce ongoing costs.
Being a beginner does not automatically mean that a regular plan is better. What matters is whether you understand the investment and can manage it responsibly.
Which Is Better for Experienced Investors?
Experienced investors who understand asset allocation, mutual fund categories and risk management may prefer direct plans.
The lower expense ratio can be particularly attractive for investors who are comfortable doing their own research.
However, even experienced investors may choose regular plans if they value professional assistance or prefer delegating some investment decisions.
Can You Switch From Regular to Direct Mutual Fund?
Investors may generally move from a regular plan to a direct plan of the same scheme, subject to the applicable process and conditions.
However, switching is not necessarily a simple change of account type.
A switch may be treated as a transaction involving redemption from one plan and investment into another. Depending on the circumstances, this can have tax implications or exit-load implications.
Before switching, investors should check the scheme’s current rules and understand the potential tax and cost consequences.
Direct Mutual Fund vs Regular Mutual Fund: Example
Suppose two investors invest in the same mutual fund scheme.
Investor A chooses the direct plan, while Investor B chooses the regular plan.
Both plans invest in the same underlying portfolio, but the regular plan has a higher expense ratio because of distribution-related costs.
If the fund generates the same gross investment performance, the investor in the direct plan may receive a higher net return after expenses.
The difference may seem small initially. However, over a long investment period, even a small annual cost difference can have an impact because the investment returns compound.
How Should You Choose?
Consider these questions before deciding.
Choose a Direct Plan If:
- You are comfortable researching mutual funds
- You can evaluate risk and returns
- You want to minimise ongoing expenses
- You prefer managing your portfolio independently
- You have enough time to monitor your investments
Consider a Regular Plan If:
- You want distributor assistance
- You are not comfortable selecting funds yourself
- You value ongoing investment guidance
- You prefer a more assisted investment experience
- You are willing to pay for the additional distribution service
Important Things to Check Before Investing
Regardless of which option you choose, don’t select a mutual fund only because it has a lower expense ratio.
Consider:
- Investment objective
- Risk level
- Asset allocation
- Historical performance
- Fund manager and fund strategy
- Expense ratio
- Exit load
- Tax implications
- Investment horizon
- Your financial goals
Past performance does not guarantee future returns, so fund selection should be based on more than historical returns.
Final Takeaway
The primary difference between direct and regular mutual funds is the distribution arrangement and associated cost.
Direct plans generally have lower expense ratios because they do not include distributor commissions. They can therefore be attractive to investors who are confident about researching and managing their own investments.
Regular plans generally cost more but provide access to distributor support and guidance, which can be valuable for investors who want assistance.
Therefore, direct mutual funds may be better for self-directed investors focused on keeping costs low, while regular mutual funds may suit investors who value professional or distributor assistance. The right choice depends on your knowledge, time, investment goals and willingness to manage your portfolio yourself.